November 1 - 30, 2026: Issue 660

Aboriginal children less likely to receive a police diversion from court in New South Wales

Tuesday November 10 2026
New research from the NSW Bureau of Crime Statistics and Research (BOCSAR) has found that Aboriginal children are substantially less likely than non-Aboriginal children to receive a police diversion from court, even when their alleged offences are eligible for diversion under the Young Offenders Act.

Between April 2022 and March 2025, 46% of eligible police matters involving Aboriginal children were diverted from court through a warning, caution or Youth Justice Conference, compared with 76% of matters involving non-Aboriginal children.

BOCSAR Executive Director Jackie Fitzgerald said differences in eligibility for diversion did not explain the disparity.

“When we restricted the analysis to matters where diversion was available to police, Aboriginal children were still 30 percentage points less likely to be diverted from court.”

Offence seriousness, bail and prior justice system contact explain much, but not all, of the gap

The study found that 72% of the 30-percentage point gap was due to differences between Aboriginal and non-Aboriginal children, including factors such as offence seriousness, bail status and prior contact with the criminal justice system.

“Even among eligible matters there can be important differences. Some eligible offences are more serious than others, and police can consider factors such as a child’s prior offending and bail status when deciding whether diversion is appropriate,” Ms Fitzgerald said.

After accounting for these and other observable characteristics, Aboriginal children remained around 8 percentage points more likely to be proceeded to court.

“We can account for much of the disparity using the information available to us, but we cannot identify what is driving the remaining 8 percentage point gap.

“There are factors that could influence diversion decisions that were not well captured in the available data, such as whether a child admitted the offence or cooperated with police. Discrimination is also a possible explanation, but this study cannot determine whether, or to what extent, it contributes to the gap.”

Disparity evident from first formal police contact

The study also examined children at their first formal police contact, to test whether the disparity in diversion persisted when differences in prior formal offending history were removed.

Even at first formal contact, around 10% of eligible matters involving Aboriginal children proceeded to court, compared with 5% of matters involving non-Aboriginal children. Around 80% of this gap could not be accounted for by the information available to the researchers.

“Prior contact with police and courts is an important part of the overall disparity, but it isn’t the whole story. We still see a difference in diversion rates at the very first formal police contact, before a history of cautions or court appearances can influence the decision.”

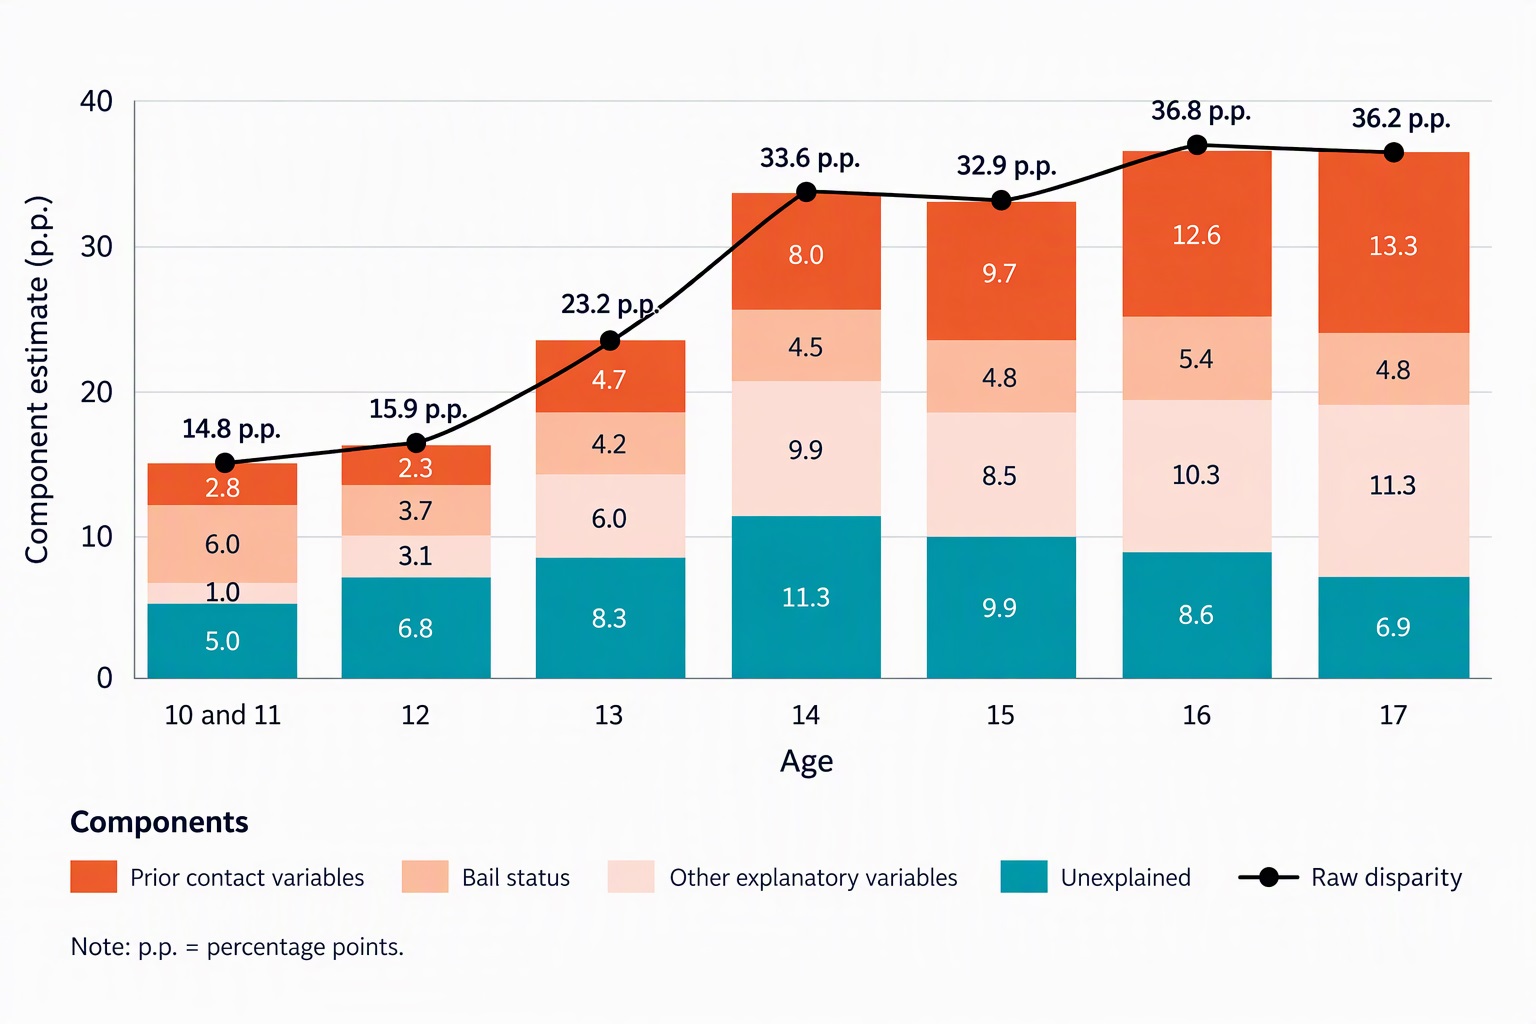
The study also found that disparity in diversion rates widened with age as Aboriginal children disproportionately accumulated contact with police and courts. By age 17, differences in prior justice-system contact accounted for almost 40% of the 36-percentage point diversion gap.

“The findings highlight the importance of reducing repeated justice-system contact and better understanding the factors affecting police decisions to divert young people, particularly for Aboriginal children.”

Examining disparities in police diversion between Aboriginal and non-Aboriginal children in NSW: BOSCAR Report
Released: November 2026
Under the Young Offenders Act 1997 (NSW) (YOA), NSW Police can deal with alleged offending by children aged 10 to 17 years through a warning, caution or Youth Justice Conference instead of initiating court proceedings. Diversion under the YOA reduces children’s exposure to the formal court process and may reduce their risk of future contact with the justice system. Previous research shows that Aboriginal children are less likely than non-Aboriginal children to receive a YOA diversion. This is concerning given that one objective of the YOA is to address the over-representation of Aboriginal children in the criminal justice system.

This study examines the size of the diversion rate disparity between Aboriginal and non-Aboriginal children from 2022 to 2025, and the factors associated with it. To do so, we use statistical decomposition to estimate how much of the disparity is associated with observable differences in offender and offence characteristics. This analysis is conducted separately for events eligible for diversion under the YOA, for children at their first formal contact with NSW Police, and across different ages.

Key findings
Between 1 April 2022 and 31 March 2025, NSW Police issued a Court Attendance Notice (CAN) in 68% of criminal events involving Aboriginal children, compared with 38% of criminal events involving non-Aboriginal children. This means Aboriginal children were 30 percentage points (p.p.) less likely than non-Aboriginal children to be diverted from court. This 30 p.p. diversion rate disparity remains when the analysis is restricted to offences eligible for diversion under the YOA.

Differences in offence and offender characteristics account for an estimated 72% of the 30 p.p. disparity among YOA eligible events. Aboriginal children are more likely to be proceeded against by police for more serious YOA eligible offences and to be on bail at the time of the alleged offence, both of which are associated with a lower likelihood of diversion. These differences account for around 10 p.p. of the disparity. More extensive prior contact with police and courts among Aboriginal children accounts for a further 11 p.p.. After accounting for all observed differences, YOA eligible Aboriginal children remain 8 p.p. less likely to be diverted from court than non-Aboriginal children.

The diversion rate disparity is smaller at first formal police contact and increases with age. At ages 10 and 11, 21% of YOA eligible Aboriginal children are issued a CAN, compared with 7% of non-Aboriginal children, a disparity of 15 p.p. (Figure 1). By age 17, the disparity increases to 36 p.p.. As children age, differences in prior contact with police and the courts (dark orange component) account for an increasing share of the disparity in diversion rates.

Graphic credit: Examining disparities in police diversion between Aboriginal and non-Aboriginal children in NSW.  Bureau of Crime Statistics and Research.

Conclusion
Aboriginal children are substantially less likely than non-Aboriginal children to be diverted away from court by NSW Police. Available data on offence and offender characteristics explain approximately 72% of the 30 p.p. diversion rate disparity. The remaining 28% of the 30 p.p. disparity cannot be accounted for by variables observed in the data.

Access full report; 
Zappia, M. (2026). Examining disparities in police diversion between Aboriginal and non-Aboriginal children in NSW. 
(Crime and Justice Bulletin No. 282). Sydney: NSW Bureau of Crime Statistics and Research.

New home loans dropped by a record 15% as Australia’s housing market downturn deepens

suburban houses in Melbourne
Linh Pham/Unsplash
Christian A. Nygaard, UNSW

New mortgage loans dropped by a record 15% in the September quarter as the housing market downturn deepened, led by a 30.6% dive in lending to investors, official figures on Wednesday showed.

The Reserve Bank’s five interest rate hikes and stagnant real wages have hit housing demand from investors, first-home buyers and established home owners. Reforms to tax rules for investors have also contributed to sinking investor demand for existing homes.

Over the year, the number of new loans taken out has dropped by 21.4% overall, with a spectacular 38.5% drop for investors.

However, reduced competition from investors may also create opportunities for first-home buyers. In the September quarter, lending to first-home buyers fell by a more moderate 8.6%.

Putting the drop in new home loans in perspective

The current drop in mortgage lending highlights the volatility of Australia’s housing market. While house prices have soared since 2000, we have also seen several marked downturns in both property values and loan issuance.

Before the current downturn, average real prices declined for at least two quarters on four occasions since 2011. The most recent downturns – those starting in March 2018 and March 2022 – lasted for at least a year.

An opportunity for home and first-home buyers?

Higher interest rates affect all homebuyers needing a mortgage. As a result, demand across investors, established homeowners and first-home buyers has declined.

However, the drop in housing investment has been steepest for investors. They constitute a large segment of housing demand and are more sensitive to expected house price and interest rate changes.

Over the year to September 2026, both the number and value of new investor mortgages declined spectacularly by 38.5%. This was mainly driven by a near 46.2% drop in the purchase of existing properties.

However, not all buyers are equally put off by the decline in house prices and rise in mortgage costs. Over the year, new loans to non-first home buyers dropped by a more moderate 8.7% and for first-home buyers 12.3%.

The pattern was similar for the value of new loans.

That shift over the past year means the share of total lending to home buyers has increased by nearly 9%. And for first-home buyers, the average loan size has increased by almost 10%.

For some home and first-home buyers, falling prices and less competition from investors may also come with improvements in access to home ownership.

A greater role for non-bank lenders

The significance of this shift towards owner-occupier lending should not be overstated. The value of new loans to investors is still 1.5 times larger than new loans to first-home buyers.

But the shift to owner-occupier lending echoes the pattern seen when tighter credit rules for investors were imposed in 2014 and 2016 to limit investor lending growth. The rules reduced the share of lending to investors, while the price of investor-acquired homes also declined relative to other housing market segments.

The tighter rules for investors were replaced by a serviceability buffer for all borrowers. This means borrowers need to be able to withstand a further 3% rate increase above the current level – or 12 standard rate rises.

But since those lending buffers only apply to lending by approved deposit-taking institutions, such as the major banks, more borrowers are turning to non-bank lenders. These are financial institutions such as La Trobe Financial or Athena Home Loans, which provide loans but offer fewer other financial services.

Over the year, major bank lending fell 7.1%, while non-bank lending jumped 67.7%, albeit from a low base.

How the house price drop has helped buyers

As house prices have fallen, more first-home buyers may be able to get into the market or to afford a better quality property.

The table below compares the monthly mortgage repayments for a home before and after a theoretical 10% price fall and six rate rises (that’s one more than the RBA’s five hikes). It shows mortgage repayments would have increased by 17.2%.

However, for a buyer who waited before entering the market, or could not purchase before the price fall, the monthly mortgage cost – compared to purchasing this property before the house price drop and six rate rises – has only gone up from $3,407 to $3,593, or 5.5%.

The economic fallout

Higher interest rates and declining house prices do not only trigger declines in mortgage demand. New housing construction in Australia responds to profitable opportunities, driven by cost of borrowing and changes in house prices.

When house prices fall, new construction typically also declines, with a lag. Slowdowns in construction activity reduce demand for materials, tradespeople and real estate professionals, thus impacting jobs and broader economic activity.

For Australian households, spending more on paying for mortgages also means less cash for other types of spending like dining out, travel and furniture and appliances.

A slide in consumer confidence figures this week confirmed the Reserve Bank Governor Michele Bullock’s comment that the current economy may feel “like a recession”.The Conversation

Christian A. Nygaard, Professor of Housing Economics, UNSW

This article is republished from The Conversation under a Creative Commons license. Read the original article.

New AI regulator announced, as government considers criminal law change to keep erring frontier companies in line

Michelle Grattan, University of Canberra

Prime Minister Anthony Albanese has announced a new artificial intelligence (AI) safety regulator, which will enforce penalties for frontier AI companies that breach their obligations.

The government is also considering criminal law changes to deal with serious misconduct by any of these companies.

The measures are targeted at frontier AI companies – those building the largest, most advanced models.

At a news conference shortly before leaving for the COP climate conference in Turkey, the prime minister outlined AI safety and security protections that will be in the government’s proposed AI framework legislation.

The six mandated requirements for companies are:

  • maintain security controls across all stages of AI development and deployment
  • identify and manage serious risks associated with models
  • quickly provide mandatory notification of incidents to the Australian government
  • allow independent evaluation of models
  • maintain and publish safety and security frameworks to ensure good governance, risk management and transparency
  • respond to updated standards and rules as technologies change.

Albanese said these protections were in line with recommendations from the parliamentary joint select committee on AI.

The government also released the recommendations from the rapid review into the OpenAI breach of an Australian government site by a rogue agent earlier this year.

In this breach, for which OpenAI apologised, statistical health data was accessed, but no personal data. The government complained strongly to the company.

“It can’t be allowed to happen again,” Albanese said on Tuesday. He said the government had accepted and commenced work on the review’s 18 recommendations.

The recommendations include:

  • mandatory AI company reporting of misaligned behaviour or cyber incidents
  • consideration of reforming criminal law to deal with cases of serious misconduct
  • greater engagement with international counterparts and frontier AI developers to promote shared expectations about AI safety and accountability
  • strengthening resilience and response to AI incidents, including better information sharing and more focus on cyber security.

Albanese, appearing with Defence Minister Richard Marles and Home Affairs Minister Tony Burke, told his news conference the government wanted to see Australia benefiting from the advantages of AI while mitigating the risks.

In relation to new criminal penalties the review report said the Attorney-General’s Department, in consultation with the Australian Federal Police, the Home Affair Department, and other agencies, should explore:

the application of criminal penalties for egregious regulatory non-compliance; and/or a standalone “failure to prevent” offence which would criminalise instances where the company is responsible for developing an AI model that engages in harmful conduct, and the company fails to take reasonable steps to prevent that harm.

Albanese said the government would release the report of the review, with due regard to national security considerations, but there is no clarity about when this will be done.The Conversation

Michelle Grattan, Professorial Fellow, University of Canberra

This article is republished from The Conversation under a Creative Commons license. Read the original article.
New Australian AI safety and security protections: Announcement

Media release: Tuesday 10 November 2026
The Albanese Government will enshrine world leading mandatory Artificial Intelligence safety and security protections in Australian AI Standards legislation.

Australia has the chance to secure and shape the generational opportunities of AI – in Australia’s national interest – while keeping Australians safe.

We want AI investors to come to Australia but first and foremost we want to keep Australians safe. That is why we are choosing to announce our approach to safety first and before a range of major international talks that will cover AI development and investment.

Safety and security are the foundation for building trust in frontier AI. Frontier AI is the term used for the most sophisticated models at the cutting edge of current technological capability. Frontier AI offers huge opportunities but also come with the highest risks to the community if they are not used safely. That is why we are acting now.

Australia has a world leading reputation for setting standards on digital safety. Our approach to AI continues to keep Australian values at the forefront.

AI offers Australia huge opportunities whether it’s boosting productivity, building economic resilience or revolutionising healthcare.

To seize these opportunities, we need to ensure social licence for AI, safety for Australians and security for our national interest.

We are announcing today that as part of the Albanese Government’s AI in Australia’s Interests agenda, strong mandatory safety and security protections will be legislated through the AI Standards and apply to all frontier AI companies that wish to operate in Australia.

The Government will propose these protections be enforced by a new targeted regulator for AI safety, which will work with the Australian AI Safety Institute to provide technical expertise and oversight as global standards evolve.

The regulator would be able to enforce significant penalties for AI companies that fail to comply with mandatory obligations that will help keep Australia safe.

Companies will be required by the regulator to: 
  • Maintain security controls across all stages of development and deployment
  • Identify and manage serious risks associated with their models
  • Allow independent evaluation of their models
  • Provide mandatory notification of incidents to the Australian Government rapidly
  • Maintain and publish safety and security frameworks to ensure good governance, risk management and transparency
  • Respond to updated standards and rules as technologies change.
These protections are aligned with interim report recommendations from the Joint Select Committee on Artificial Intelligence.

These measures will help provide earlier warning of emerging risks from rogue AI agents and enable faster, coordinated action when serious AI incidents occur.

As previously outlined, there are a range of other policy areas covered in the Australian AI Standards legislation. Further details of the legislation will become available in due course as the Government completes its detailed work and consultation.

The Australian Prime Minister, the Hon. Anthony Albanese stated:
"Artificial intelligence presents enormous opportunities for Australia, but we must also be prepared for the new risks that come with rapidly advancing technology.

"These protections will ensure we keep Australians safe and secure our national interests, while seizing the generational opportunities that AI offers.

“Our world-leading AI in Australia’s Interests agenda aims to provide Australians confidence that frontier AI companies are taking steps to improve safety and security, and provide certainty for investors – boosting productivity, building economic resilience, while bolstering sovereignty.”

Deputy Prime Minister and Minister for Defence, the Hon. Richard Marles stated:
“Getting these settings right will help ensure Australia can harness the opportunities artificial intelligence presents for our economy, our national security and our sovereignty.

“The Albanese Government is committed to putting in place the protections that will allow Australia to be at the forefront of this technology to keep Australians safe.”

Minister for Home Affairs and Cyber Security, the Hon. Tony Burke, stated:
“Those who want to cause us harm have access to the latest technology.

“We need to make sure we have the same, or better.

“But it’s not a free-for-all, there needs to be clear guardrails to protect Australians.”

Minister for Industry and Innovation, the Hon. Tim Ayres, stated;
“Keeping Australians safe is at the heart of the Albanese Labor Government’s approach to artificial intelligence.

“The National AI Plan released last year put safety at the core of the Government’s AI agenda - capturing the opportunities of AI while keeping Australians safe.

“Legislating protections as part of the Australian AI Standards will build on the work of the National AI Plan, helping Australia spread the benefits of AI across the country, while making sure that AI systems are developed and deployed in Australia’s national interest.

“Strong protections will ensure that Australia has the capacity to shape our own technological future and build our economic resilience.”

[The Australian Government released the 18 recommendations from the rapid review into the OpenAI Medicare statistics portal breach on the same day. The full review report itself has not been published. Prime Minister Anthony Albanese stated that the full report is being kept private in the interest of national safety and security.]

Strengthening Australia against AI-driven cyber incidents

Media release: Tuesday 10 November 2026
The Albanese Government is today releasing the recommendations of the Rapid Review into the OpenAI agent infiltration of an Australian Government health website.

The Review was commissioned in September after OpenAI informed the Australian Government that a rogue AI agent had infiltrated government websites, including the Medicare Statistics Reporting Service Portal.

As we said at the time – and made clear to the CEO of OpenAI, Sam Altman – this incident was unacceptable, the disclosure was inadequate and it couldn’t be allowed to happen again.

When it comes to the generational opportunity that AI offers Australia, my Government has been very clear.

We must make sure we shape AI, rather than AI shaping us.

AI needs to work in Australia’s interests. And humans must remain in control.

To seize these opportunities, it is critical we: 
  1. Provide safety for Australians and keep their data secure
  2. Keep our national security data protected in our national interest.
  3. Ensure AI companies have a social license to operate
The Rapid Review – undertaken by the Department of Prime Minister and Cabinet, in collaboration with the National Cyber Security Coordinator, Office of AI, Australian Signals Directorate, Australian AI Safety Institute, and Services Australia – makes 18 recommendations, including: 
  • Mandatory AI company reporting when it comes to misaligned behaviour or cyber incidents
  • Consideration of reforming criminal law in cases of serious misconduct
  • Greater engagement with international counterparts and frontier AI developers to promote shared expectations regarding AI safety and accountability
  • Strengthening resilience and response to AI incidents, including improved information sharing and a renewed focus on cyber security.
The Government accepts the recommendations and has commenced work to implement them. The recommendations can be found here:


Rapid Review into Australian Government arrangements for an AI‑driven cyber incident recommendations

The Rapid Review into Australian Government arrangements for an AI-driven cyber incident examines the OpenAI cyber incident affecting Services Australia and outlines 18 recommendations to ensure Australia is better prepared for AI incidents of greater scale, complexity and consequence.

The Rapid review into Australian Government arrangements for an AI-driven cyber incident recommends:

1. The Australian Government strengthen mechanisms for engagement and information exchange with frontier AI developers, including through participation in relevant international initiatives and expert fora, personnel exchanges, and technical collaboration.

Actions include to:
a) engage with OpenAI's Australian Taskforce and similar initiatives, and
b) explore secondments, personnel exchanges and technical placements with frontier AI firms.

2. In order to maximise leverage with frontier AI firms, the Australian Government continue to encourage frontier AI firms to establish research, training and safety-related activities in Australia.

3. The Australian Government consider mandatory, time-bound AI safety reporting, including but not limited to misaligned behaviour or agentic cyber incidents.

4. The Australian Government explore options to support timely reporting of AI cyber or safety incidents and near misses – for example, protections relating to AI incidents and vulnerability disclosures from AI developers (and others with relevant knowledge), analogous to existing Limited Use protections.

5. The Office of AI consider how Australia’s AI Standards should leverage existing, accepted regulatory and law-enforcement mechanisms by international counterparts, to help build common AI safety and security expectations.

6. The Department of Foreign Affairs and Trade (DFAT), the Australian Signals Directorate (ASD), and the Department of Industry, Science and Resources (DISR), including Australia’s AI Safety Institute (AISI), continue engaging in international AI governance and standards-setting efforts to promote consistent expectations regarding safety, incident reporting, evaluations, safeguards and transparency.
a) This work be coordinated with Australia’s broader international AI engagement, including efforts to secure advanced AI capabilities and attract trusted investment.

7. The Australian Government consider the role AISI plays in future to deliver against increasing demands for technical research, evaluation and analysis on AI, including its capacity to support the proposed AI Standards and their requirements, international engagement on AI standards and norms, and to provide necessary rapid scientific and technical advice and analysis during crisis coordination (See Recommendation 11).

8. The Attorney-General’s Department (AGD), in consultation with the Australian Federal Police (AFP), the Department of Home Affairs (Home Affairs), and other relevant agencies, consider options to reform the criminal law to improve AI safety, including exploring:
a) the application of criminal penalties for egregious regulatory non-compliance; and/or
b) a standalone ‘failure to prevent’ offence which would criminalise instances where the company is responsible for developing an AI model that engages in harmful conduct, and the company fails to take reasonable steps to prevent that harm.

9. The Protective Security Board, informed by advice from Home Affairs and ASD, issue Protective Security Policy Framework (PSPF) policy guidance to clarify agency obligations and escalation expectations, where reported vulnerabilities or suspected cyber security incidents have not yet been technically validated.

10. Commonwealth agencies review vulnerability-disclosure and cyber incident-management procedures to ensure they align with PSPF requirements, support timely escalation of novel or unusual incidents, and provide clear pathways for reporting matters to ASD, Home Affairs and senior decision makers.

11. Operational agencies and agencies with coordination, policy or enabling responsibilities must ensure timely information sharing. In relation to cyber incidents, consideration be given to establishing formal liaison arrangements between ASD’s Australian Cyber Security Centre (ACSC), the National Office of Cyber Security (NOCS) and AISI to support improved information sharing, coordination, and the early identification of incidents with broader national-interest implications.

12. Commonwealth agencies clarify response procedures to ensure the organisation responsible for consequence management in response to a cyber incident (the NOCS) determines whether consequence management arrangements are required, enabled through enhanced information sharing (per Recommendation 11).

13. Commonwealth agencies responsible for national plans under the Australian Government Crisis Management Framework (AGCMF), and their underpinning procedures, consider the impact of AI on the hazards and arrangements they manage, and write to Crisis Arrangements Committee Chairs with outcomes of this work and any proposed changes by the end of 2026, ahead of the next update to relevant national plan or procedures.

14. Commonwealth agencies take action to uplift the AI literacy of relevant staff to strengthen their ability to respond to AI-related risks.

15. Commonwealth agencies renew their focus on the fundamental elements of good cyber security practice, including implementation of ASD’s Essentials.

16. Commonwealth agencies work to reduce the size of the government digital estate, consolidating digital systems, and shutting down or segregating systems that do not need to be connected to the internet.

17. The Australian Government consider how to further harden cyber defence of Systems of Government Significance, including considering a changing threat environment and risk profile.

18. Commonwealth agencies engage with ASD to identify and assess opportunities to responsibly use AI-enabled cyber defence tools and techniques to enhance cyber security monitoring, penetration testing, threat detection and incident response capabilities.

Spin can't conceal total capitulation to vampire AI corporations: Greens

On the same day, Tuesday November 10, the Australian Greens stated the  ''Albanese-Labor government’s announcement of a toothless regulator as the result of a PMO managed and Labor controlled committee process is another predictable capitulation to the interests of vampire US tech corporations over Australian people. 

The recommendations maintain Labor’s plan for a massive national roll out of US data centres. They don’t include a single new legal power to curb the behaviour of these extractive corporations as they pertain to community consultation, environment, energy consumption, water consumption or copyright.''

Greens Leader, Senator David Shoebridge, said:
“Australians are demanding a moratorium on new AI data centres and today Labor gave us all a word salad instead.

“This review is Albanese all over, messaging over substance and pretend reform in a desperate attempt to paper over his total surrender to US demands.

“The Prime Minister had the gall to announce another regulator without the powers and protections needed to hold these corporations to account. 

“It’s utterly bizarre that just weeks after OpenAI was implicated in hacking a Medicare portal the Government’s key recommendation is to get closer to OpenAI.

“Sending public servants on secondment to the companies they’re meant to regulate is how regulators get captured. When those companies are vampire US AI companies the risks of this strategy are obvious. 

“The weak recommendations in this review fall well short of responding to the real and growing public concern, a case in point is that even OpenAI supports mandatory reporting, while the PM only promises to “consider” it. 

“Another recommendation is to “explore” protections for people reporting those incidents and vulnerabilities. These fundamental safety obligations should be mandatory.

“Safety keeps coming second to corporate investment, and this review locks that priority in by tying every AI safety effort to bringing in more AI money and more data centres.

“The Greens have joined calls from around the world for a binding international AI treaty, and all the government can offer here is more of the same talk at international forums.

“A report like this can only come from a captive agency controlled by a Government that is more interested in managing the messaging around AI than actually delivering the safety and control communities are calling for. 

“AI data centres are sucking power out of the grid pushing power prices up for all of us, sucking construction workers out of the housing build and driving inflation, stealing artists' work, and Labor announces another toothless, powerless regulator with no new legal powers to stop them.

“Being a world leader in AI doesn’t mean being a doormat to big tech. It means being prepared to regulate it, to protect Australians and to make sure corporate profits don’t come at the expense of everyone else.”

ASIC issues interim stop orders against two Angas Securities funds over PDS and Bathla disclosure concerns

Monday November 9 2026
ASIC has made interim stop orders preventing Angas Securities Limited (Angas Securities) from offering interests in two managed investment schemes over concerns the funds’ product disclosure statements (PDSs) do not adequately disclose Angas Securities’ financial position and one fund’s exposure to the Bathla Group.

The interim stop orders prevent Angas Securities from offering, issuing, selling, or transferring interests in the Angas Prime Income Fund (ARSN 091 887 400) and the Angas Direct Mortgage Fund (ARSN 151 979 645).

ASIC is concerned that investors in both funds may not have been adequately informed about the financial position of Angas Securities and the risks arising from that position.

ASIC also has concerns about disclosures to investors in the Angas Prime Income Fund relating to its exposure to the collapsed Bathla Group and the risks arising from that exposure.

ASIC Commissioner Simone Constant said, ‘Our message to private credit fund managers is crystal clear. Investors need clear and timely information about the risks they are taking on, particularly when circumstances change and private credit loans run into difficulty.

‘The collapse of the Bathla Group has highlighted the risks that can emerge in private credit when this message is ignored. The Bathla collapse drives home the importance of strong governance, appropriate valuations and clear disclosure to private credit investors.

‘ASIC is engaging closely with voluntary administrators to trace the $3.2 billion in funds loaned to Bathla and making a range of inquiries focused on taking further action as appropriate. One of our main concerns is to understand the extent to which there are retail investors affected.

'ASIC will continue its broader scrutiny of private credit and will continue to step up our actions. We will act swiftly where we are concerned investors are not being given the full picture about the risks they face,’ Commissioner Constant said.

ASIC is concerned that:
  • The Angas Prime Income Fund PDS does not adequately disclose a range of material information, including its exposure to Bathla Group borrowers, defaults, liquidity, loan-to-value ratios, portfolio diversification and that information about loan to valuation limits is not presented in a clear, concise and effective manner.
  • The PDSs for both the Angas Prime Income Fund and Angas Direct Mortgage Fund do not disclose material information about Angas Securities’ own financial position, including a net asset deficiency, breach of net tangible asset requirements, and proposed capital raising, or what could happen to the funds if Angas Securities cannot raise sufficient capital to continue as a going concern.
ASIC will consider whether final stop orders should be made after giving Angas Securities an opportunity to be heard.

ASIC will publish the results of its next private credit surveillance on Tuesday 10 November 2026.

Background
Angas Securities holds Australian financial services licence 232479 and is the responsible entity of the Angas Prime Income Fund and the Angas Direct Mortgage Fund.

As at 30 June 2026, the funds held approximately $114 million in investor funds, comprising $78.6 million in the Angas Direct Mortgage Fund and $35.1 million in the Angas Prime Income Fund.

The two funds provide exposure to mortgage lending but operate using different investment structures. The Prime Fund is a pooled mortgage fund, and the Direct Fund is a contributory mortgage fund.

Angas Securities’ financial statements state that the crystallisation of a loss on a first mortgage loan investment (not directly related to the Bathla group) caused it to breach the net tangible asset requirements applying under its Australian financial services licence and it is undertaking a capital raising, which its directors expect to be resolved by 31 December 2026.

Helping Australians navigate financial decisions in an increasingly complex information environment

Address by ASIC Commissioner Alan Kirkland at the Ecstra Financial Wellbeing Summit in Sydney on 10 November 2026

Good morning.

I’d like to begin by acknowledging the Gadigal people of the Eora nation and by paying respects to elders past and present and I extend that respect to Aboriginal and Torres Strait Islander people in the room with us today.

When I spoke here last year, I talked about how consumers in the financial system are often vulnerable to exploitation because in almost every decision they make, they’re equipped with less knowledge than the person or the firm on the other side of the transaction.

ASIC’s work in the past year has continued to reinforce this point.

We saw it in our review of mortgage offset accounts, where customers were potentially paying more interest than they should because of banks’ failures to properly set up, monitor or manage offset accounts.

We saw it in our review of car insurance, where customers were in the dark as to why their premiums were rising sharply and repeatedly.

And we saw it in our review of cash settlements in home insurance claims, where many offers were based on quotes from insurers’ preferred suppliers.

Different products, different circumstances, but they underscore the same point:

In a financial system that is becoming harder to navigate, financial wellbeing can’t depend on consumers simply getting better at navigating complexity.

We need to reduce the risk of harm, provide trusted help when people need it, and understand what actually helps people to make better decisions.

And that’s what I’d like to talk to you about today.

The new consumer environment
For a long time, financial capability was largely framed as an ‘information problem’: if people had access to the right information, they’d be better equipped to make good decisions.

I think that everybody in this room recognises that the challenge is more complicated than that.

Consumers today have access to more financial information than ever before. The problem is knowing what and who to trust.

Information comes at consumers from every direction - from social media, targeted advertising, influencers and increasingly AI. And the line between information, marketing and advice is not always obvious.

Scams are becoming increasingly hard to spot.

ASIC is seeing that with the increasing number of pump and dump schemes reported to us, where scammers are often using AI-generated, deep fake videos of well-known personalities and fake news sites to promote investments.

So, a question for all of us to consider is: how do we help people distinguish information that serves them, from information designed to manipulate them?

Adding to the complexity of the issue is the fact that many consumers have a level of anxiety about their financial future and are actively looking for guidance on how they can improve their financial security.

This creates an environment where there is an increased risk of consumer harm, and where we need to work even harder to help people to find their way to information they can trust.

Moneysmart as a trusted source
Moneysmart remains the pre-eminent destination for those seeking trusted financial advice, guidance and resources on a broad range of products and issues.

But in the era of AI, consumers are increasingly not ending up in destinations like Moneysmart but instead are being served AI-generated answers on their phones.

It’s the latest iteration of what has been a changing information landscape since the advent of search engines.

For ASIC, it means doubling down on our strategy of ‘meeting people where they are’, but we are competing with an ecosystem that is pumping out content – some valuable, lots harmful - at scale.

That means that building financial capability increasingly involves building digital financial literacy – the ability to distinguish between different information sources, separate truth from hype, and understand the strengths and weaknesses of AI tools.

It also means working closely with key stakeholders, especially when it comes to assisting consumers who have suffered financial harm.

A current example of this is our work to engage with consumers affected by the Shield and First Guardian collapses which the Minister mentioned earlier.

This is no small task. Over 11,000 people lost money through these collapses – with some having lost their entire retirement savings.

Many only invested after being convinced to move their super by lead generators, who often obtained consumers’ details via social media ads that purported to offer ‘free super reviews’ or ‘super health checks’.

A key goal of our communications has been to encourage those affected to lodge complaints with AFCA because for many, that may be the only pathway to compensation.

At the same time, we have been using every opportunity to warn other consumers how to avoid falling victim to the same harmful lead generation techniques.

While our work is far from done, we have learned some valuable lessons.

There are three in particular that I’d like to call out.

Firstly, we need to communicate harm in ways that reflect consumers’ actual experiences.

In our early communications relating to Shield and First Guardian, we described ‘high pressure sales tactics’ that were being used to convince people to switch their super into high-risk investments.

While our investigations have shown that warning was well-founded, feedback from investors suggested that it didn’t accurately describe what had happened to them.

I’ve listened to many of the call recordings that we’ve gathered in our work and they weren’t overtly high-pressure. They came across as friendly, helpful and informed. They were certainly persuasive but in a gently persistent, rather than pushy, manner.

Adopting different language in our communications has meant that our messages resonate better with those affected, as well as providing better and more effective warnings to others who may be potential victims.

Secondly, steps that seem simple to all of us (like lodging a complaint) can feel complex and overwhelming to consumers - especially those who have experienced a traumatic event.

Back in February, less than 2,000 of the 11,000 investors had lodged a complaint and that number has now doubled to around 4,000.

Through the 14 rounds of emails and direct mail we have sent to various groups of investors, we’ve come to realise that rather than focusing on bombarding people with information on their rights, we need to make taking that first step as simple as possible.

For many Shield and First Guardian investors, the business models were so complex, that they didn’t know who they should lodge a complaint against or for what reason. It was important for us to make the process as easy as possible.

And that brings me to my third insight – that we cannot do it alone, particularly in situations where so many people are affected.

For Shield and First Guardian, we have worked closely with Super Consumers Australia, who have set up a dedicated website that provides simple, easy-to-digest information on what happened, how to make a complaint and how they may be able to get some money back.

Importantly, this includes an easy-to-use, partially pre-filled complaints form that allows people to simply tick boxes in key areas, rather than working out what they need to say.

This is work that is more easily done by a consumer organisation than a regulator, and it’s played an important role in lifting the complaint numbers.

The other thing that we have done through the process is keep in contact with key investor representatives, who have told us what sorts of questions investors need answered, and when our communications were not hitting the mark.

This is not an approach that we can take in response to every fund collapse, but the extraordinary circumstances of Shield and First Guardian required extraordinary responses, and the lessons we’ve learned will be useful in a range of our other financial literacy work.

Getting better at knowing what works
Which leads me to my final point:

We need to get better at understanding what works and we need to find new ways of engaging with consumers.

Over the past year, we’ve completely revamped the Moneysmart website and built a high-quality social media presence.

In the age of AI summaries, we can no longer rely on the old metrics of hits to a website or advertisement reach as a marker of success.

Instead, we need to embrace the harder and more important challenge of changing behaviour, and measuring whether we are succeeding.

That is the key driver behind research we have done with RMIT to develop a financial wellbeing index which we intend to use to measure behavioural change.

And it’s also the reason that ASIC supported Australia's participation in the OECD Adult Financial Literacy Survey – which was informed by the clear support for that step in the room at last year’s summit.

ASIC regards sharing research and insights with the broader financial wellbeing community as an important part of our role, recognising that the goal of building financial capability is shared by people working across government, the community sector and industry.

We’re planning an insight sharing session for early 2027 where we’ll share the results of the OECD survey. If you’d like to know more about the financial wellbeing index or the OECD survey in the meantime, please speak to Jackson Hewett or Andrew Dadswell who are both here today.

Conclusion
If there’s one thought I’d like to leave you with today, it’s this: Financial wellbeing isn’t just about putting more information into the system.

It’s about understanding what helps people to make better decisions, giving them trusted places to turn, and designing a financial system that supports rather than tests their ability to navigate it.

ASIC looks forward to working with all of you to do just that.

Why chronic pain is often overlooked as part of disability – and what can help

Woman looking out the window.
shurkin_son/Getty
Manasi Murthy Mittinty, The University of Melbourne; Anne Kavanagh, University of Sydney; RMIT University, and Sophie Yates, Australian National University

One in five Australians lives with chronic pain, meaning pain that persists longer than three months. Among people with disabilities, the rate is far higher.

Yet this overlap between disability and chronic pain is still misunderstood.

Even if someone is on the National Disability Insurance Scheme (NDIS) for a disability, they may not get adequate support for how pain also affects their functioning and interacts with their other impairment/s. Many people with chronic pain are not eligible for the NDIS, despite it having a severe, ongoing impact.

Here’s why this approach doesn’t make sense – and how upcoming changes to NDIS funding could make it even more complicated for people to get the support they need.

The impact of ongoing pain

Chronic pain is far more than an unpleasant sensation.

Along with eroding physical health, living with pain can also disrupt relationships, work, financial security, mental health and wellbeing. People who live with chronic pain face a higher risk of unemployment and depression than those without it.

How severely pain affects someone depends on their personal and social circumstances, such as their age, sex, relationships, social connection and culture.

Disability and chronic pain are interrelated

Getting NDIS support depends on someone proving their impairment or impairments reduce their ability to do everyday tasks (their functional capacity). This includes self care, mobility, communication and taking part in community and social activities.

Chronic pain is generally not enough to qualify for NDIS support, unless you can prove it significantly impacts your functioning in this way.

But it can be tricky to disentangle the impact of chronic pain from other impairments. Pain can both arise from and contribute to long-term health conditions and disability. For example, living with pain can amplify other aspects of someone’s disability, such as mobility.

There also aren’t many effective medications to treat chronic pain; the way it’s managed often overlaps with disability support. This might include allied health (such as physiotherapy), home modifications and assistive technologies (including handrails, adapted utensils or transcription software), and direct support for tasks that exacerbate pain (such as gardening or cleaning).

So for some people who live with chronic pain and have permanent impairments, it doesn’t make sense to separate their pain and its impact from their disabilities.

A woman in a wheelchair waters her garden with a hose.
Support for everyday tasks is rarely affordable without NDIS funding. Centre for Ageing Better/Unsplash

NDIS changes may hit people with chronic pain

Chronic pain is also often misunderstood as only a medical issue that needs to be “fixed” rather than a long-term condition.

From January 2028, to be eligible for NDIS services and supports, people will need to have “undertaken all appropriate treatment” for their condition and it must be assessed as likely to be permanent.

However, we don’t know what treatments could be considered “appropriate” for chronic pain related to impairment/s – or whether all such treatments would need to be tried before someone can access the NDIS.

New rules also say NDIS participants can only access supports that address needs arising “directly” from an NDIS-recognised diagnosis or impairment. However, this may not reflect the interconnected ways disability and chronic pain affect people’s lives.

NDIS participants may be able to get support for pain if it arises from the diagnosis or condition that made them eligible for the NDIS. But if pain occurs for a reason deemed unrelated to those accepted diagnoses, they may miss out.

Imagine an NDIS participant with multiple sclerosis (MS) who falls and sprains their ankle. Maybe they tripped and fell because of weakness or balance problems their MS caused. But it may be hard to prove the ongoing pain relates to MS.

Under the new legislation, it’s unclear if their existing physiotherapist could charge for treatment and rehabilitation from their ankle injury, how the person would prove it was related to MS, or if they’d require a separate appointment, not funded by the NDIS, to treat the ankle sprain.

Support outside the NDIS

So, what if you live with chronic pain but you’re not eligible for the NDIS?

People with chronic conditions can access Medicare-subsidised allied health through a GP chronic condition management plan. But this only covers five visits a year across a variety of allied health professionals and may incur out-of-pocket expenses.

Some people may pay for these services in full or receive some rebates through private health insurance or, if an injury is work-related, through workers’ compensation schemes.

But for people without NDIS funding, support for daily tasks such as personal care or chores are rarely affordable. Federal, state and territory governments have agreed to more supports in the community, outside the NDIS – known as “foundational supports” – but they have not yet been implemented for adults, and many questions remain about how they’ll work.

We need better coordination

Amid significant NDIS reform – including tighter eligibility and funding cuts to allied health – there is a risk more people with chronic pain could fall through the cracks.

Without adequate support, we will see a flow-on effect. For people living with disability and chronic pain, their ability to take part in social life and employment, and to maintain their physical and mental wellbeing, is likely to be limited.

We need better coordination between different service systems including Medicare, private health insurance and the NDIS, and more support for those with complex needs.

Some may need health care, while others may require practical support with community access, mobility or personal care to take part in the community, move around, and do everyday tasks like dressing and preparing meals.

The goal should be simple: the support people receive should reflect the life they are trying to live, not just their diagnosis or disability.


We would like to acknowledge Helen Dickinson from the University of New South Wales and Alexandra Devine from The University of Melbourne for their contribution to this article.The Conversation

Manasi Murthy Mittinty, Senior Research Fellow, Disability and Health Unit, Department of Health Systems, Policy and Economics, Melbourne School of Public Health, The University of Melbourne; Anne Kavanagh, Professor, Centre for Disability Research and Policy, University of Sydney; RMIT University, and Sophie Yates, Senior Research Fellow, Crawford School of Public Policy, Australian National University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Australians are paying ‘extreme’ specialist fees. Here’s how the government can rein in costs

Xavier Arnau/Getty via Canva, Gerardo Huitron/Getty via Canva, Pixelshot/Canva, The Conversation, CC BY-NC
Peter Breadon, Grattan Institute and Thomas Shortridge, Grattan Institute

Seeing a specialist keeps getting more expensive, and a new Grattan Institute analysis shows the problem is getting worse, not better.

After years of inaction, reform may finally be on the agenda.

At the end of last year, Health Minister Mark Butler said fees to see medical specialists – such as paediatricians, dermatologists and psychiatrists – were “out of control”. The government has launched a parliamentary inquiry, and the federal health department has consulted on a range of reform options.

To make specialist medical care affordable, the consultations and inquiry must trigger overdue reform to train more specialists, fund more free public clinic appointments, and rein in the most extreme fees.

Specialist fees are out of control

Our 2025 report, Special Treatment, found that between 2010 and 2025, fees for specialist care outside hospitals grew 73% in real terms (meaning adjusted for inflation). That is many times faster than for GPs or other Medicare services. Since then, fee growth has continued unchecked. In the past year alone, specialist fees rose 4% faster than inflation.

Some specialties have seen especially steep rises. The median out-of-pocket fee for an initial psychiatry appointment is now A$351, up $90 in real terms in the past two years. The median initial dermatology appointment costs $217, up $28.

At the same time, fee-free care is dwindling. Fewer than a quarter of initial specialist appointments are now bulk-billed, down from about a third a decade ago. In urology, dermatology, psychiatry, and ear, nose and throat (otolaryngology), it’s fewer than one in ten.

And the most expensive specialists are pulling further ahead.

The priciest 5% of psychiatrists charge a median of $669 for an initial appointment, and their fees have risen $58 a year faster than inflation.

The most expensive paediatricians charge $362, triple what their peers charge. Their fees have risen $50 a year in real terms, compared with just $3 among the other 95% of paediatricians.

Some specialists charge, on average, more than triple the Medicare Benefits Schedule (MBS) fee – the basis for government funding (for care outside hospital; patients usually get back 85% of the MBS fee).

While we argue these can only be described as extreme fees, they are becoming more common. Last year, 2.2 million patients paid at least one extreme fee, more than four times the number a decade ago.

Don’t blame Medicare, or costs

Doctors’ groups blame Medicare rebates for not keeping up with inflation. It’s true government rebates have fallen in real terms, but fees have risen far faster. Since 2012, the average specialist rebate has fallen $9 in real terms, while average out-of-pocket costs have risen $37.

In psychiatry, the rebate for an initial appointment has fallen $44 in real terms since 2012. Fees rose by much more than that in just the past year.

Rising practice costs don’t explain it either. Tax data show private specialist practices’ costs grew just 1.8% a year in the 15 years to 2024–25 – slower than inflation – while their profits grew.

The specialist market is broken

Specialist fees are rising because the usual checks on price are missing. In most markets, if you charge too much, customers go elsewhere. With specialists, there’s often nowhere else to go.

Many areas don’t have enough specialists, especially outside the big cities. The free option, a public clinic, can mean waiting months or even years.

Even when there is a choice, patients aren’t well placed to make it. A GP’s referral is the biggest influence on which specialist a patient sees, and many don’t find out the price until they’re handed the bill. And when facing a health scare, patients might not have time to shop around.

The hard reforms remain

Governments have started to act.

The parliament has passed legislation to publish individual specialists’ fees, and the health department has consulted on bigger reforms. Victoria has funded more specialist clinic appointments for children, and several states are establishing systems to give GPs quick access to specialist advice, so that patients don’t need to make a separate appointment.

But these are mostly the easiest, cheapest steps, and not the ones that will make the biggest difference.

In our 2025 report, we recommended that the federal government set clear training targets for each specialty. The targets should dictate where funding for trainee places goes across the specialties, and how many are in rural areas. Then specialist colleges should be held to account for achieving them. The May budget rolled over existing specialist training funding for another year, without adding new places.

We also recommended governments invest $500 million a year in building the capacity of public clinics, targeting areas with the worst wait times. Extra funding should expand clinics, build new ones, and make telehealth available where it’s the best option.

Better information about fees is good. But it won’t help if you can’t afford them and face a year-long waiting list for a public clinic.

It’s time to rein in extreme fees

Training more specialists and expanding public clinics is essential. But this will take time, and fees are rising every year. That’s why governments must also tackle extreme fees directly.

We recommend a simple rule. If a specialist’s fees average more than triple the MBS fee across a year, they should repay the Medicare rebates for their services that year. Patients would keep their rebates, so the penalty falls on the specialist, not the patient.

This threshold is deliberately high. Averaging across a whole year leaves room for legitimately high fees, such as those for complex patients or long appointments. It would only affect about 6% of all specialists, and they wouldn’t be able to avoid it by shifting fees around. That small minority charge around half of all extreme fees, and almost all the very highest fees.

Charging unjustifiable fees is a choice. It should be a costly one for specialists, not for patients.The Conversation

Peter Breadon, Program Director, Health and Aged Care, Grattan Institute and Thomas Shortridge, Associate, Health Program, Grattan Institute

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Powerhouse Parramatta: a museum of science, design and technology supercharged by spectacular art

A room containing a mirrored maze, with a person in a pink shirt standing in the centre looking up and reflected in the surfaces.
Es Devlin: Forest Of Us. Romello Pereira/Powerhouse Parramatta
Joanna Mendelssohn, The University of Melbourne

The first marvel is the light.

There are so many published images of the new Powerhouse museum’s steel exoskeleton that it is hardly a surprise when two dazzling white structures like giant milk crates suddenly emerge from the depressing jumble of modern office buildings that characterise modern Parramatta.

But the light inside the building is something else, as glass walls invite the sky outside to come in.

Exterior of a two-towered building covered in a white steel exoskeleton, seen within a natural landscape with a river running through.
Powerhouse Parramatta is a $915 million project, designed by Moreau Kusunoki and Genton. Ben Hoskings/Powerhouse Parramatta

An exhibit you can paddle in

Daylight is a key element in Overflow, one of the museum’s five opening exhibitions.

In a large open space with views to the Parramatta skyline and river below, a giant video screen plays a series of short films by Kamilaroi filmmaker Ivan Sen, showing seven different First Nations communities in New South Wales caring for their saltwater and freshwater country. Images of riverbanks, lagoons and sandy beaches are reflected in a shallow replica tidal pool in front of the screen.

Contemporary museums pride themselves on interacting with visitors, but this is the first time I have seen a museum encouraging people to wade into an exhibit.

A large gallery space with natural light, with a giant LED screen showing a landscape, and a shallow pool of water in front of it.
Overflow features films by Ivan Sen and a shallow pool that rises and falls with the tides of the Parramatta River. Hamish McIntosh/Powerhouse Parramatta

A kids exhibition themed around darkness

According to the ceaseless political campaign against the Parramatta incarnation of the Museum of Applied Arts and Sciences, the original collection has been abandoned in favour of novelty. This is not true. Most of the works in The Dark, an exhibition specifically devised for children, come from the permanent collection.

Darkness here is a friend, not foe. Displays of beautiful minerals and precious stones are captioned with stories of the people who discovered them.

Those of us who are old enough to remember the eccentricities of the original museum in Ultimo can rediscover the pleasures of mechanical birds that sing with a pressed button, and the transparent woman whose body parts light up on command.

Another display features precious personal items lent by local children. Curatorship becomes community engagement.

A darkened gallery space with a massive, glowing replica of a meteor, with a small lit tunnel leading into it.
Visitors are asked to leave their smartphones outside before entering The Dark, the Powerhouse’s exhibition for children and families. Sean Fennessy/Powerhouse Parramatta

A tribute to the shopping mall

The Powerhouse’s permanent collection also underpins The Mall, a celebration of the products, design and community life of the shopping mall.

There are arcade window displays and a re-imagined version of the beloved Raindrop Fountain inside Roselands shopping centre. Objects on display include an old-fashioned photobooth, antique cash registers and the original “Parramall” neon sign.

The David Jones archive, now a part of the Powerhouse collection and on display in the exhibition, includes mid-20th century advertising posters and photographs of window displays. It’s a window into a time when DJs was the epitome of style.

A commissioned series of portraits by photographers Jo Duck and Bahram Mia captures those who shop, socialise and work in today’s malls.

A gallery space designed like a retro shopping centre meeting space, with a replica fountain with lights instead of water.
The Mall is co-designed by Powerhouse curators with global architecture, design and research studio OMA*AMO. Cieran Murphy/Powerhouse Parramatta

An ode to flight and space exploration

The largest and most hyped exhibition is Task Eternal, an exploration of flight – from a Burramattagal bumarang (boomerang) on loan from the British Museum to machines enabling exploitation of the moon.

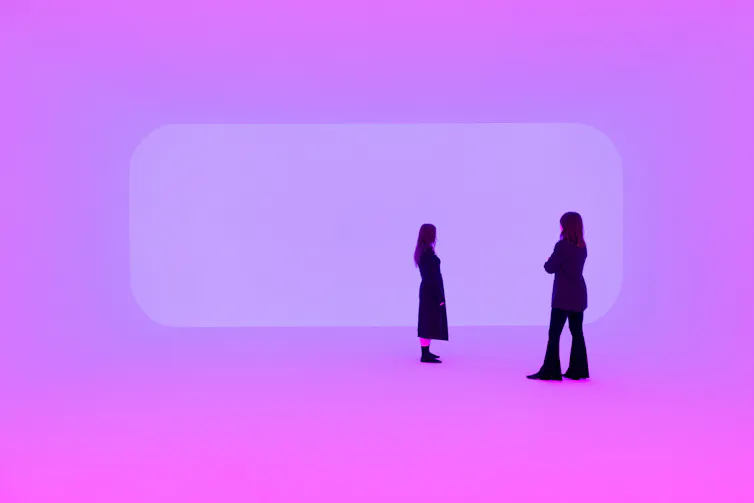
The commissioned artworks include an immersive installation by American light artist James Turrell. The specially designed room evokes the disorienting Ganzfeld effect through an intense field of changing coloured light.

A small chamber lit with crimson light, in which two figures are seen standing in sillouette.
James Turrell is best known for his ganzfeld installations, which combine design and light to conjure perceptual confusion. Sean Fennessy/Powerhouse Parramatta

The curators, working with Chinese design firm OPEN Architecture, have created a nuanced investigation of wonder.

Leonardo da Vinci’s surprisingly fresh sketches of imagined flight sit alongside the Powerhouse’s collection of drawings and models by Australian aviation pioneer Lawrence Hargrave, who helped shape the 20th century’s achievement of an ancient fantasy.

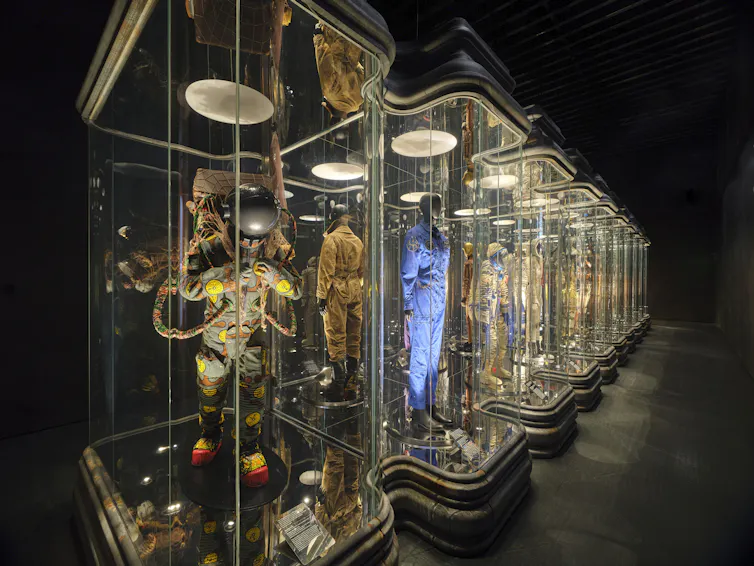
There is an Apollo space capsule, aeroplanes and rockets, copies of messages sent with the Voyager craft on its endless journey into deep space, space suits – and space junk.

One of the most compelling exhibits is a digital display of the pollution now destroying the night skies, showing how this vandalism has taken less than a lifetime to “achieve”.

A darkened room containing crennellated glass cabinetry containing space suits.
Task Eternal includes a room full of space-wear, including costumes from science-fiction classics like Alien and space suits from different eras. Sean Fennessy/Powerhouse Parramatta

Es Devlin: The Turning

The fifth exhibition, The Turning, showcases recent works by British artist and designer Es Devlin, whose practice spans stage design, sculpture and installations, arena concerts by the likes of U2 and Lady Gaga, and large-scale events including the opening ceremony of the London Olympics.

The Turning opens with the Forest of Us, a meditation on organic symmetry. Visitors enter by walking past the sentence: “Every time I reach a fork in the road, I take both paths”.

These words lead visitors to a short, poetic film on the nature of organic symmetry. At the end of the film a door appears in the middle of the screen and the viewer walks into a giant mirror maze, beautiful and disorienting.

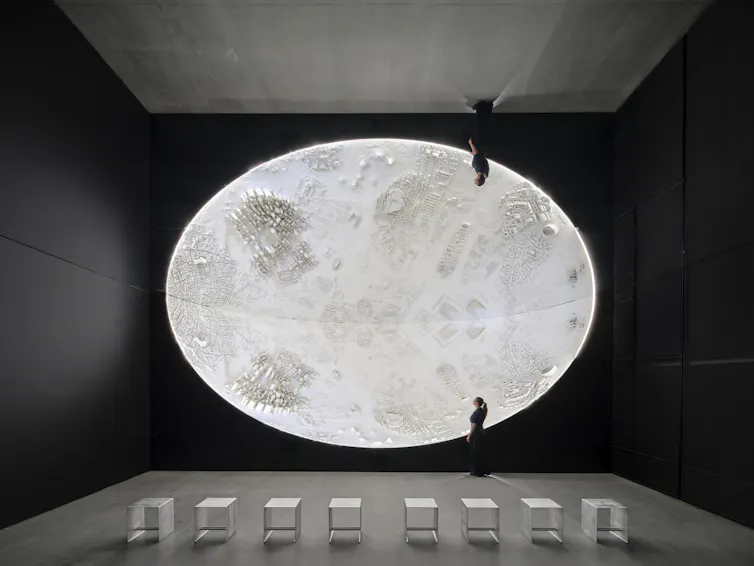
Memory Palace, a 3D-printed imaginary city composed of key sites throughout history, cites American cultural anthropologist Margaret Mead:

Never doubt that a small group of thoughtful, committed citizens can change the world; indeed, it’s the only thing that ever has.

In audio narration, Devlin lists places including the bus stop where Rosa Parks waited, the stadium stage where Martin Luther King spoke, the town hall steps where Greta Thunberg sat and the Block at Redfern, a key site of Australian First Nations activism.

A gallery with dark walls and an ovoid installation showing a 3D printed cityscape in white, with stools positioned in a row in front.
Es Devlin’s Memory Palace debuted in London in 2019. For Australia, she presents an updated iteration including local sites. Romello Pereira/Powerhouse Parramatta

In the next room, people are invited to sit at a long table for 15 minutes and draw a stranger opposite them, looking in their eyes without speaking. This work, titled Collective Portrait, is an actualisation of Devlin’s belief that the act of recording is a reminder that we are all part of a living universe.

On the lawn outside the Powerhouse, Devlin’s drawings of 244 endangered local species have been collaged into an egg-shaped stage. This forms the backdrop for Devlin’s performance work Come Home Again (first staged in London), featuring choral tributes to vulnerable species. The work will be performed at dusk from Thursday to Sunday during November, as part of the Powerhouse’s opening festival.

By any measure, Parramatta is lucky to be able to experience in depth the work of such a major art star.

Supercharging the community

“Powerhouse” has become a popular name for arts centres. Usually they are repurposed industrial buildings, made redundant by technological change. This Powerhouse is named in honour of its history and also, I suspect, in hopes of the impact it will have on both its surrounding suburbs and the wider community.

So far, so good.

Powerhouse Parramatta is open 10am-5pm daily, and until 9pm Thursday-Sunday during November as part of its opening festival. Entry is free.The Conversation

Joanna Mendelssohn, Honorary Senior Fellow, School of Culture and Communication, The University of Melbourne

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Opera Australia’s La Bohème captures the romance of bohemian Paris with a fresh twist

Opera Australia/Peter Foster
Brian Long, The University of Melbourne

Paris in the 1830s and 40s danced on the edge. Napoleon was dead. The Bourbon royals were back. Revolutions in 1830 and 1848 brought pitched battles to the streets. Glitzy wealth rubbed up against dire poverty.

Yet the city was a honey-pot for 20-something creatives; meet the bohemians. These brooding, passion-infused romantics dominated the art world. Chopin was there penning some of the most romantic piano music ever written. Victor Hugo’s Hunchback of Notre-Dame came out in 1831.

Among these dreamers was Henry Murger, a jobbing writer living hand-to-mouth. In 1849, he penned a series of autobiographical sketches glamourising his friends, lovers and exploits.

Murger’s tales were a runaway success. But it was Italian composer Giacomo Puccini who immortalised them with his 1896 opera La Bohème, based on Murger’s 1851 novel Scènes de la vie de bohème (Scenes of Bohemian Life).

La Bohème sealed Puccini’s fate as arguably the greatest opera composer of all time. Opera Australia now brings a fresh look to this eternally popular masterpiece.

The new production brings to life Puccini’s vision of the bustling streets of bohemian Paris. Opera Australia/Peter Foster

Puccini’s timeless tale

Rather than spinning a grand plot, La Bohème drops us into four scenes spanning a Parisian winter. Four young down-and-out creatives are following their dreams. But there’s not enough food to go round. They torch the furniture to keep warm. The rent hasn’t been paid for three months.

It is two great love affairs that warm the hearts of audiences as much as they do those of the two leading men, Rodolfo and Marcello. La Bohème lives on quick-fire dialogue among rough-and-tumble young men, but illness and frailty lurk throughout. In the end, tragedy strikes.

Murger’s tale has been repackaged various times in pop culture, including in the 1990s rock musical Rent. Young love, glamour, infatuations, jealousy and loss never tire as theatrical crowd-pleasers.

Luke Gabbedy as Marcello, Stephen Marsh as Schuanard, David Parkin as Colline and Kang Wang as Rodolfo in Opera Australia’s La Bohème. Peter Foster/Opera Australia

A bold, vibrant and vivacious take

Opera Australia’s production opened at Melbourne’s Regent Theatre on Saturday. Director Constantine Costi and his team have come up with a contemporary, vivacious and playfully cheeky take on an old favourite.

The leading man, Rodolfo, comes over as a sensitive, slightly over-awed young man. Decked out in green velvet, he is closer to a boy-band heartthrob for the TikTok era than to the traditional Italian lover.

Kang Wang has a fine, compact voice to match. His first act aria on opening night needed to project a bit more, but his presence grew as the night progressed. This Rodolfo is not going to sweep you off your feet. He is too 2026 for that – but he still has many endearing features.

Costume designer Sabina Myers channels Parisian painters of the 1920s to produce a whole catalogue of vivid looks. Her coat for Mimi, Rodolfo’s great flame, pays homage to French artist and designer Sonia Delaunay and Orphism – an offshoot of Cubism.

Fresh from a run as Mimi in Munich last year, Galina Cheplakova makes her Australian debut in the role. Strongest in the high register, she brings a coy smile to her first encounter with Rodolfo and luxuriated in the soaring vocal lines as she recalled the first April sun in her lonely loft.

Act two sees our Bohemians at a famous Parisian cafe. This act made the most demands on the opera’s original creatives. Two writers penned numerous versions before Puccini was happy.

The effort paid off handsomely. The chorus and lead singers toss snappy jokes between each other. Split-second timing is essential, and the Opera Australia team pulls it off brilliantly.

Marcello’s old flame Musetta, played by Alexandra Flood, steals the show at Cafe Momus. Coiffed with a wonderful roaring ‘20s look, she knows how to turn heads. Her sugar daddy tags along but can’t keep up. Flood plays the femme fatale with bravura and a flair for sartorial provocation.

Alexandra Flood knows how to turn heads as Musetta, Marcello’s old flame. Peter Foster/Opera Australia

Parisian flair at the Paris end

La Bohème can pose a challenge for directors. The opening and final acts need intimacy. Act two, on the other hand, portrays a bustling street scene with kids, crowds and marching bands. Going too far in either direction risks making the show feel disjointed.

Set designer Dann Barber neatly dodges this bullet with tightly masked apartment scenes, and a hot-air balloon that floats the lovers from Rodolfo’s dingy loft into the let-it-rip colour and Marc Chagall ambience of the street outside Café Momus.

Lovers Mimì and Rodolfo float away in a hot-air balloon. Peter Foster/Opera Australia

The Regent Theatre takes pride of place at the “Paris end” of Collins Street and makes a beautiful, traditional venue for La Bohème. Yet it lacks an orchestra pit. Orchestra Victoria sits at the front of the stalls and the stage is set well back – sacrificing some immediacy in the drama.

Conductor Finnegan Downie Dear, in his Australian debut, works hard to keep the orchestra from overloading the cast – but this comes at the cost of some lushness in Puccini’s orchestral writing.

Opera Australia has a hit on its hands. No matter if you’re falling in love with Puccini’s gem for the first time, or if it’s an old favourite, this bouncy new Bohème will enchant newcomers and devotees alike.

La Bohème is showing in Melbourne until November 18, and opens in Sydney on January 2, 2027.The Conversation

Brian Long, Lecturer in Arts and Cultural Management, The University of Melbourne

This article is republished from The Conversation under a Creative Commons license. Read the original article.

ACCC warns against misleading ‘storewide’ or ‘limited time’ Black Friday sales claims

November 10 2026
The ACCC is continuing its crackdown on promotional and advertising practices that could mislead consumers, launching another sweep across multiple retail sectors during the Black Friday and Cyber Monday sales period.

The third sweep of its kind will look at potentially misleading conduct, including the use of:
  • ‘Sitewide’ or ‘storewide’ claims, when actually a large number of products are excluded from the sale,
  • Time-limited offers and countdown timers, when the offers continue beyond the stated end date,
  • Promotional tactics to pressure shoppers to make purchases, including misleading testimonials and scarcity messaging, such as false claims that stock levels are low.
  • Advertisements comparing sale prices to a misleading reference price, when those items were never, or not recently, sold at those reference prices.
For the first time, this year’s sweep will examine retailers’ advertising practices across multiple channels, including websites, emails, and social media. This reflects the growing range of ways consumers now engage with companies and are reached by their advertising. 

The sweep will also assess how promotional practices have changed over time, including emerging tactics, and will consider whether retailer compliance with the Australian Consumer Law has improved in the past three years.

“Consumers continue to look for the best prices and may delay major purchases until Black Friday and Cyber Monday in anticipation of good value and legitimate discounts,” ACCC Deputy Chair Catriona Lowe said.

“Consumers should be able to trust that the advertised savings and discount prices are genuine, but we know some businesses use tactics to mislead consumers into thinking they are getting a bargain even when they are not.”

“Retailers risk ACCC enforcement action if they misrepresent the size, scope or duration of their sales. Retailers should not be relying on fine print disclaimers or exclusions to qualify the headline message of a promotion,” Ms Lowe said.

Retailers must ensure their sales and discount claims are accurate, clear and not likely to mislead or deceive consumers. Retailers should review ACCC guidance on false or misleading claims when preparing their promotions.

Consumers are encouraged to focus on the end price of a product, not on promotional claims. This includes checking for any exclusions or conditions, and comparing prices between retailers and over time where possible. They should carefully consider the advertised price and buy only if the price and time is right for them.

“Consumers should be aware that a ‘sale’ sign doesn’t always mean it’s a good deal,” Ms Lowe said.

Examples of the type of advertising that the upcoming sweep will focus on
Example of a retailer that advertises a ‘sitewide’ sale when in fact there are a range of products which are excluded from the sale.

A fine print disclaimer is not sufficient to qualify the headline message of the promotion.

Example of the use of a countdown timer

Countdown timers, if not accurate, can create a false sense of urgency.

Example of a misleading price comparison, where the ‘strikethrough’ price is not a price that the product had been recently sold at

Background
The 2024 and 2025 Black Friday sweeps uncovered concerning sales advertising practices in Australian retail.

Following these sweeps, Michael Hill, My House and Hairhouse Warehouse Online paid penalties in June 2025, and digiDirect, James Lane and Vuly paid penalties in September 2026, for allegedly making false and misleading representations about their Black Friday Sales.

During Black Friday and Cyber Monday sales, consumers should also check they are buying from a legitimate seller and be especially alert to fake online shop fronts. These often use large discounts and "limited time" sales to encourage people to buy quickly and without confirming they are buying from a genuine online shop. 

In the first nine months of 2026, 58.7 per cent of Scamwatch reports that included a financial loss were about buying and selling scams.

ACCC issues Linfox Armaguard with interim direction to support ongoing access to cash

On November 5 2026 the ACCC gave Linfox Armaguard Pty Ltd (Armaguard) an interim direction that requires it to continue to supply cash in transit services and provide access to its facilities to its customers across Australia, and that sets the terms on which Armaguard provides these services.

The interim direction does not override existing contracts between Armaguard and its customers, and allows Armaguard and its customers to negotiate new agreements on different terms. The direction applies to existing Armaguard customers and a small subset of new customers.

In August this year, the Australian Government passed laws that gave the ACCC new powers to regulate cash distribution services, reflecting the essential role that cash continues to play in the economy.

The ACCC has now used its transitional powers to give an interim direction in relation to Armaguard’s cash in transit services and facilities access that applies until 30 June 2027. Armaguard is Australia’s biggest provider of these services.

With the interim direction in place to support ongoing supply to customers on fair and reasonable terms, the ACCC will now consider longer-term regulatory settings to support a reliable and sustainable cash distribution system.

“Australia is in a critical period in which reliable access to cash is still important for many consumers and businesses, but the cash-in-transit industry is under pressure due to the significant decline in cash use,” ACCC Chair Gina Cass-Gottlieb said.

“Without this regulatory intervention, we consider there would be potential risks to the continued supply and availability of cash in Australia. We also note that this is a highly complex situation, involving customers of many different sizes in urban, regional and remote parts of the country.”

“Our interim direction strikes a balance in the short-term between considering Armaguard’s financial position and providing a level of price and non-price clarity and stability to Armaguard, retailers, banks and other businesses that still use cash,” Ms Cass-Gottlieb said.

“We have carefully set the terms of the interim direction with a view to the longer-term settings for the sector. Those settings will take into account the availability and viability of cash, economic efficiency, the public interest, Armaguard's legitimate business interests, and employee compensation as a key cost of providing these services.”

Armaguard recently submitted a proposed undertaking to the ACCC in relation to its interim prices, service offering and national coverage, among other things.

“We conducted extensive consultation on Armaguard’s proposed undertaking, including directly with Armaguard and many of its customers,” Ms Cass-Gottlieb said.

“The ACCC considered a wide range of material, including the proposed undertaking, and the perspectives of the many stakeholders involved. We also conducted our own analysis on different approaches.”

“We believe our interim direction is, at this time, the most appropriate short-term response to a complex situation. Importantly, we have flexibility to adapt or modify our regulatory settings should we need to,” Ms Cass-Gottlieb said.

“We will continue to engage closely with all parties on the longer-term settings for cash distribution services.”

The obligations the interim direction places on Armaguard include that:
  • it must continue to supply services and access to approved cash centres to businesses that are currently receiving those services or access.
  • there are different maximum price paths for different sized customer groups.
  • previous non-price terms that applied at 30 June 2026 continue.
  • it must not unreasonably discriminate in favour of its own operations or one of its related body corporates in its dealings with independent ATM customers and third-party cash-in-transit providers.
The interim direction and explanatory statement can be accessed through the ACCC website: Cash Distribution Framework transitional arrangements.

More information about the ACCC's role in relation to cash is available on the ACCC website: Cash Distribution Framework.

Background
The cash-in-transit industry is in structural decline due to the decreasing use of cash as a payment method across the Australian economy. However, cash use has stabilised in recent years and it continues to be crucial to certain customers and parts of the economy.

The RBA designated Linfox Armaguard under the Cash Distribution Framework Act on 3 September 2026, meaning Armaguard became subject to legal obligations administered or enforced by the ACCC under the Act.

Under the legislative framework, the ACCC can issue an interim direction to a designated entity requiring it to provide cash distribution services or facilities access to a customer on terms specified in the interim direction.

Designated entities can also submit a court enforceable undertaking to the ACCC on matters relating to the CDF Act at any time. Linfox Armaguard provided a proposed undertaking to the ACCC on 23 September 2026.

Linfox Armaguard and Prosegur, the two main providers of cash distribution services at a national level in Australia prior to 2022, sought ACCC clearance to merge in 2022.

In 2023, the ACCC approved the merger subject to a legally enforceable undertaking which contained a number of commitments by Linfox Armaguard relating to pricing, non-price terms, supply of services and other matters.

That previous undertaking expired on 4 September 2026.

The ACCC also previously authorised arrangements for a number of parties to discuss, share information, reach agreement on and/or implement (as relevant) a number of assistance measures for the purpose of supporting wholesale cash viability and access to cash by businesses and members of the public, including short term financial contributions to Armaguard.

That authorisation expired on 30 June 2026. There are no ongoing short term financial contributions being provided under those arrangements.

I don’t want AI in my online search. What options do I have?

A woman stands in a cityscape searching on a tablet with a digital illustration overlay of connected dots.
Weiquan Lin/Getty Images
Damiano Spina, RMIT University

Last week, Google announced a new artificial intelligence (AI) policy for schools that use Google apps. It provides new settings for opting in or out of AI products on student accounts. For schools that reject AI in the classroom entirely, they can also turn off search.

Speaking to The New York Times, Google’s vice president for education, Chris Phillips, noted that “search and AI are deeply integrated”. This led to headlines claiming there’s no longer a way to use Google search without AI.

Since AI has become ubiquitous, it’s also facing increasing pushback. Some people may reject it due to personal, ethical, or environmental reasons.

But we all need to look things up on the internet. So is it actually possible to search the web “without AI”? To answer that question, we need to unpack a few things first.

How does a web search engine work?

Google search is a tool known as a web search engine. For you to type in a query and receive results milliseconds later, a bunch of things need to happen under the hood. All of them involve algorithms – simply put, a set of instructions for a computer.

There are six main components of a web search engine:

  • crawling: harvesting documents published on the web
  • indexing: breaking down documents into efficient data structures
  • spam detection: filtering out content that doesn’t offer genuine value to users
  • ranking: ordering search results by how relevant they might be to the query
  • user interactions: assisting users when they formulate their information needs (for instance, auto-completing your query) or consume the search output (such as serving you snippets or AI summaries)
  • evaluation: measuring if search quality improves after making a change in one of the above components.

These features are not static – developers, engineers and informational retrieval researchers are constantly tinkering and improving them.

How does web search use AI?

To answer this question, we first need to define what kind of AI we’re talking about.

All of the components listed above are likely to involve some sort of machine learning and neural networks – that is, AI systems trained to analyse lots of data, learn patterns and make predictions. So, there’s actually no way to use a search engine “without AI”.

But when people talk about AI these days, they tend to mean generative AI. These are AI systems trained on enormous amounts of data and capable of generating new content from prompts.

A version of this, called retrieval-augmented generation, is what allows you to have a conversation with a search engine. It combines a large language model for the generative part, and the web content retrieved by the search engine.

This is the technology behind Google’s AI Mode and AI Overviews. They provide handy summaries and a new way to interact with content on the web, but they’re not without issues.

The large language model is built on an astonishing amount of training data, but it’s not updated as frequently as the web search index. Links in AI summaries are associated with the answer after generating it, and this component can also make mistakes.

In addition, searchers who see AI Overviews are accessing fewer sources overall. Overreliance on AI is also a well-known phenomenon in which users may trust an answer without verifying whether it’s correct.

So can I search the web without AI summaries?

Commercial web search engines like Google are increasingly showing AI summaries to users’ queries. At the time of writing this, there’s no official switch that lets Google users disable AI Overviews and other generative AI features.

But there’s one little hack that works: if you append “&udm=14” to the search request link, the Google search results default to the “Web” tab that doesn’t show AI Overviews and other snippets.

A screenshot that shows the search results for Naarm without AI overview and defaulting to 'web' tab.
An example of ‘Web’ results in Google search. Google

For this to work, you’d have to manually add that parameter in the address bar. That’s not always practical, so people have built browser plugins and ways to automate this step.

In Mozilla Firefox and Chromium browsers such as Brave, Chrome and Opera for desktop devices, you can set up a custom search engine to add this parameter every time you hit search on Google.

But Google search isn’t the only search engine available. There are many others out there, such as DuckDuckGo, Brave Search, or Ecosia. These provide a “non-AI mode” that deactivates AI summaries by default, and in some cases even provides the option to filter out AI-generated images.

Where do those search engine results come from?

Maintaining a web index is not easy. The web is constantly changing, and keeping the big volume of searchable information fresh requires enormous computational resources.

There are only a few organisations able to maintain this at a large scale. Google’s and Microsoft Bing’s indexes are the most popular worldwide. But there are some alternatives that are gaining attention.

Brave Search operates from an independent search engine. DuckDuckGo combines multiple sources, including content harvested with its own crawler, and search results sourced from Bing.

Initiatives such as the OpenWebSearch.eu project aim to develop an independent open European infrastructure for web search. It also makes a web index publicly available so others can build their own web search engine.

So, is there a search without AI?

The short answer is “no”. All search engines use AI in one form or another.

What about generative AI specifically?

It is technically possible to disable AI-generated answers from the search results page. Some search engine providers have decided to provide that option to users, while others – like Google – have made it a default.The Conversation

Damiano Spina, Senior Lecturer, School of Computing Technologies, RMIT University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Did Australia’s cricket leaders sandpaper over the truth? New ball tampering revelations suggest so

David Rowe, Western Sydney University

When sandpaper comes to mind, it usually relates to a weekend trip to a suburban hardware store. Yet, the Australian men’s cricket team has somehow turned this humble home maintenance staple into a symbol of scandal.

In a 2018 Test series against South Africa, captain Steve Smith and fellow batters David Warner and Cameron Bancroft were exposed for conspiring to tamper with the ball (using sandpaper to create an aerodynamic imbalance) during the third match in Cape Town.

This so-called “Sandpapergate” led to a media storm and widespread condemnation, including by Australian Prime Minister Malcolm Turnbull.

The three players were suspended and fined.

The scandal was widely revisited in the sport media when the team returned to Cape Town in October during the Test series in South Africa.

Now, the scandal is back in the spotlight after retired batter Usman Khawaja, who was on the 2018 tour, began promoting his soon-to-be published autobiography, Sabr.

What did Khawaja reveal?

The most telling revelation from Khawaja was that Sandpapergate was not a rogue enterprise involving just three players – he said in a media interview: “it was all of us. Not the batters, not the bowlers, not the staff. All of us.”

The official Cricket Australia (CA) line that it was a one-off infraction by a fraction of the team, is therefore cast into serious doubt.

But the governing body recently insisted: “all relevant information presented to CA to date has been properly considered and we remain comfortable with the findings of our integrity process.”

Khawaja claims he unsuccessfully urged the whole dressing room at the time to take collective responsibility, but it was just “those three guys [who] got crucified”.

He also stated sandpaper had been used on the ball by Australia in the previous Test match in Port Elizabeth/Gqeberha.

The changing narrative

Sandpapergate never entirely passed into history, with continuing scepticism that the hasty investigation and determination by CA was designed to cauterise the wound rather than explain how the disease had spread.

The four leading Australian bowlers on that tour released a statement in 2021 responding to a media interview with Bancroft implying others were in the know.

Current captain Pat Cummins, Mitchell Starc, Josh Hazlewood and Nathan Lyon declared: “we did not know a foreign substance was taken onto the field to alter the condition of the ball”, pleading for “an end to the rumour-mongering and innuendo. It has gone on too long and it is time to move on”.

Khawaja’s incendiary comments and dedicated Sandpapergate chapter in his book contradicts that narrative. It vividly reveals the scandal has not gone away, and his insider account cannot be dismissed as mere uninformed speculation.

What is ball tampering?

Roughening one side of the ball to gain “reverse swing” is against the laws and spirit of cricket.

But it is widely believed ball tampering is as old as cricket itself, and that an “arms race” earlier this century involved all Test match nations. Most international teams, including South Africa, England and India have found themselves in the ball tampering dock.

Still, some wicked pleasure was taken in the humiliation of an Australian men’s team described in two commissioned, independent post-Sandpapergate reports as having an “arrogant” and “controlling” culture.

Why this is hugely harmful to cricket

Those who care little for sport will wonder what all the fuss is about, as there are many more important outrages in the world than some elite sportsmen bending the rules. But it must be appreciated that sport is suffused with Olympian myths of honourable competition and respect for opponents and the game itself.

Test cricket, in particular, remains as something of a bulwark against the large-scale commercialisation of sport, including its own “fast food” forms like Twenty20.

It provides nostalgic glimpses of a gentlemanly antiquated world represented by its apologists as enlightened and benign.

When twinned with nationalism and masculinity, cricket is lavishly celebrated by the likes of long-serving Australian Prime Minister John Howard, who in 1997 declared:

All my life I really have regarded being captain of the Australian cricket team as the absolute pinnacle of sporting achievement and really, the pinnacle almost of human achievement in Australia.

That brand of cricketing romanticism is always ripe for a fall from grace.

What happens now?

So, what will result from this latest episode of the Sandpapergate melodrama?

Cricket Australia will be pressured to reopen the case. Captain Cummins, his fellow bowlers, and the rest of the 2018 tour party are now under renewed suspicion.

The “Sandpapergate three” may feel empowered, even compelled to tell their stories.

Khawaja can expect strained relations with some former colleagues as he promotes a book suggesting they committed the original sporting sin: failing to back up your mates.The Conversation

David Rowe, Emeritus Professor of Cultural Research, Institute for Culture and Society, Western Sydney University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
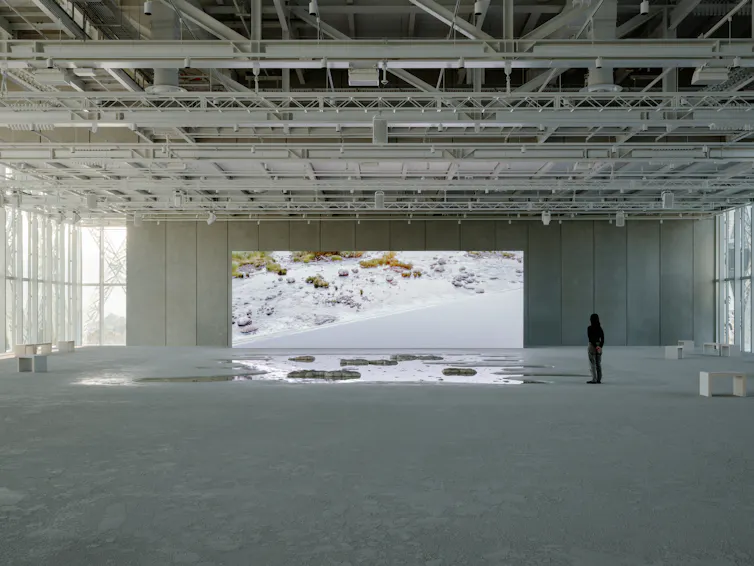
The stroke risk younger adults may be overlooking – and the symptoms that should never be dismissed

A woman grips the wall for balance while holding onto her head in pain.
Ahmet Misirligul/ Shutterstock
David Olawade, University of East London

Stroke is often seen as a condition that only affects older people. Yet the incidence of stroke in older people has actually fallen in recent decades. At the same time, rates of stroke in under-55s has been on the rise.

In England, stroke incidence among 35- to 54-year-olds rose by about 2% a year between 2001 and 2010, even as overall rates dropped. In Oxfordshire alone, stroke rates in under-55s were about 90% higher in 2010–2018 than in 1981–1986 – while rates in older people fell.

The US tells a similar story, with stroke rates in 20- to 54-year-olds rising from 34 to 62 cases per 100,000 people a year between 1993-1994 and 2020.

Globally, nearly 2.8 million people under 55 had a stroke in 2021, almost 90% of them in low- and middle-income countries. Between 2020 and 2030, it’s projected that rates of ischaemic stroke (the most common type, which is caused by a blood clot) among 20- to 39-year-olds will rise by about 12%.

What is fuelling the rise?

The rising rates of stroke in young people largely appears to be driven by things we can change.

A large international study identified ten modifiable risk factors which accounted for around 92% of strokes that occurred in people under 55. These factors included high blood pressure, physical inactivity, high cholesterol, poor diet, obesity, smoking, heart problems, diabetes, alcohol consumption and psychosocial factors (such as stress or poor mental health).

High blood pressure alone accounted for almost half of the strokes that occurred in people aged 55 and under. Lack of regular exercise accounted for more than a third.

A UK study, which looked at 1,765 people aged 18-49 who were hospitalised for a stroke, found 42% of patients had high blood pressure, 24% high cholesterol, 23% smoked and 14% had diabetes. About 7% reported recreational drug use.

Rates of obesity and diabetes have been rising in younger people for three decades. These conditions, along with high blood pressure, are often undiagnosed or undertreated in younger adults.

But left untreated, these health problems can quietly raise stroke risk. For instance, research found that under-55s with diabetes were about 3.5 times as likely to suffer a stroke or mini-stroke than those who didn’t have the condition. Those with high blood pressure were about 2.5 times as likely.

But these factors don’t explain everything. Around half of strokes in young people that were caused by a blood clot had no clear cause. Research also shows a growing number of the strokes experienced by young people have no known risk factor.

Researchers are now investigating alternative risk factors, including air pollution, autoimmune conditions and illicit drug use. Stress and overworking are also increasingly being linked to higher risk of stroke in young people.

Lack of awareness is part of the problem, too, as my systematic review showed. People who don’t see themselves as at risk are less likely to visit their doctor or change their lifestyle. Alongside risk factors that already go undetected, this may partly explain why stroke rates in younger adults haven’t fallen as they have in older people.

The signs young people miss

Stroke in younger adults can be easier to miss as well.

A man wearing a hospital gown sits on the edge of a hospital bed while a male doctor or nurse wearing blue scrubs comforts him.
Signs of stroke may be missed or dismissed in under-60s. Halfpoint/ Shutterstock

A large US analysis found that people aged 18-44 were the age group most likely to be sent home from emergency departments with a missed stroke, often after complaining of dizziness or headache. A Stroke Association survey also found a quarter of stroke survivors aged 60 and under said they were initially misdiagnosed.

The signs of a stroke in younger people can sometimes be different than they are in older people. While most people will look out for symptoms such as face drooping on one side, arms that can’t both be lifted and speech that’s slurred or confused, young people don’t always fit this pattern.

Strokes at the back of the brain, which affects balance and vision rather than the face and arms, are more common in young adults. In these cases, symptoms can manifest as problems with balance or eyesight, a headache, neck pain or vertigo.

Not only can these symptoms be missed by healthcare workers, young people themselves may explain them away as a migraine, tiredness, a hangover or an inner ear problem. Symptoms can also stop after a short time. Even if they do, you should still get medical help immediately.

Speed matters. Clot-busting treatment generally has to be given within 4.5 hours of symptoms starting. The sooner it’s given, the better the outcome and recovery.

What you can do

The good news is that most strokes in younger people are linked to things we can change.

The first thing you can do to lower your risk is to know your blood pressure. High blood pressure usually has no symptoms, so it’s important to have yours checked. You should also get checked for diabetes and high cholesterol, especially if you’re overweight or have a family history of heart disease or stroke.

Lifestyle matters, too. Don’t smoke, avoid recreational drugs and keep alcohol to no more than 14 units a week. It’s also recommended you eat less salt (no more than 6g a day) and more fibre, as these will help keep your blood pressure and cholesterol down.

Exercise is also key. Aim to get at least 150 minutes of moderate activity a week, such as fast walking or cycling.

You should also take stress and long working hours seriously. Both have been linked to a higher risk of stroke in their own right, even after accounting for other risk factors such as high blood pressure and smoking.

Stroke is no longer just an older person’s problem. Knowing the signs, and acting fast, could save your life or someone else’s.The Conversation

David Olawade, Lecturer, Department of Allied and Public Health, School of Health, Sport and Bioscience, University of East London

This article is republished from The Conversation under a Creative Commons license. Read the original article.
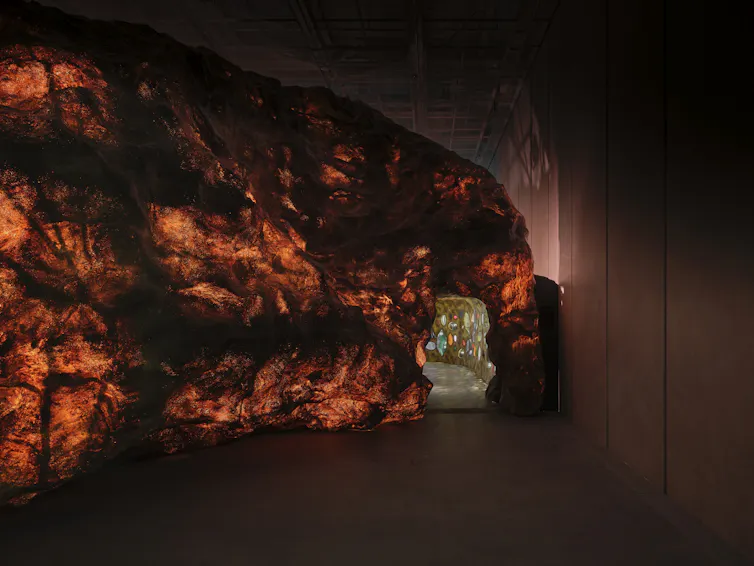
Disclaimer: These articles are not intended to provide medical advice, diagnosis or treatment.  Views expressed here do not necessarily reflect those of Pittwater Online News or its staff.